Operators — particularly those expanding from value-add acquisitions into ground-up development — frequently conflate construction loans and bridge loans. They share some surface characteristics: both are short-term, both are floating-rate in most institutional products, and both are eventually replaced by permanent financing. But they serve entirely different project phases, are underwritten against different risk frameworks, carry different recourse requirements, and interact with JV equity in distinct ways. Choosing the wrong instrument — or applying for a bridge loan when your project needs construction financing — creates delays, mispricing, and structural misalignment that adds real cost to a deal. This guide provides a definitive comparison for Georgia developers in 2026.
"A construction lender underwrites a plan and a team. A bridge lender underwrites an asset. Knowing which you're presenting — and to whom — is the first step to efficient capital execution."
What Construction Loans Do
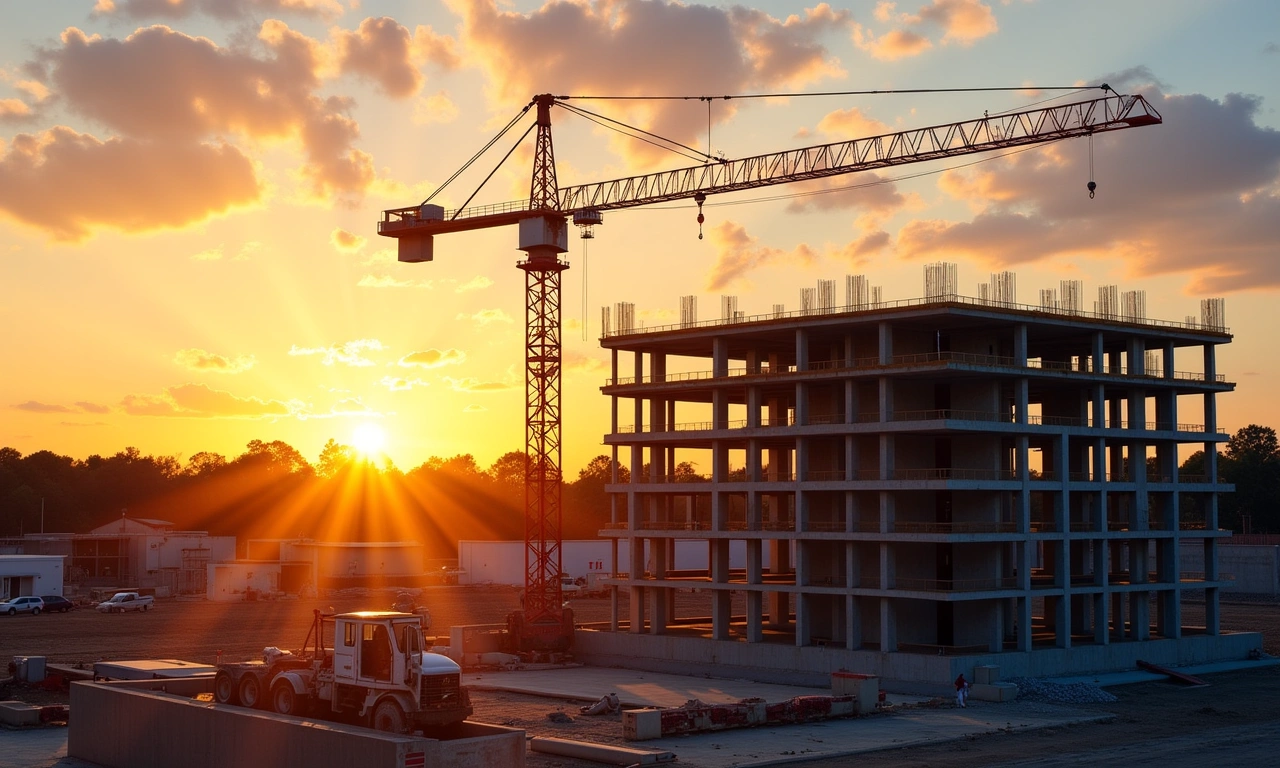
A construction loan funds the physical creation of a real estate asset from ground up — or substantial rehabilitation of an existing asset. The fundamental characteristic of a construction loan is that it funds future value creation, not present stabilized cash flow. Because the asset does not exist in its stabilized form at the time of underwriting, construction lenders face a fundamentally different risk profile than bridge or permanent lenders: completion risk, cost overrun risk, market risk during the build period, and absorption or lease-up risk post-completion.
Construction loans are disbursed in draws — tranches advanced as construction milestones are completed and verified by the lender's third-party inspector. This draw structure means the full loan amount is not outstanding on day one; interest accrues only on drawn amounts. To manage the interest carry during construction (before income is available to service debt), most construction loans include a built-in interest reserve — a portion of the loan commitment set aside to fund monthly interest payments during the build period.
Construction loans in 2026 are priced at a floating rate over SOFR, typically SOFR + 300–550 basis points, resulting in all-in rates of approximately 8.5–11% depending on project type, sponsor track record, and loan-to-cost ratio. LTC ratios typically run 65–75% of total project cost (including land, hard costs, and soft costs). Terms run 18–30 months for most mid-size projects in the North Fulton County market.
Critically: construction loans are almost universally full recourse. Lenders require a completion guaranty (the sponsor guarantees the project will be completed regardless of cost overruns) and a payment guaranty (the sponsor guarantees debt service). These guaranties can represent the most significant personal liability a developer carries on any single transaction.
What Bridge Loans Do and When They're the Right Tool
A bridge loan is a transitional financing instrument applied to an existing asset — one that is already built, or substantially complete, but not yet stabilized or generating the income needed to qualify for permanent financing. Bridge loans fund the gap between a property's current state (transitional, underperforming, or recently acquired) and its target stabilized state (fully occupied, income-producing, permanent-loan eligible).
The underwriting basis for a bridge loan is fundamentally different from a construction loan: the bridge lender underwrites to as-is value (what the property is worth today) and as-stabilized value (what it will be worth once repositioned). The lender advances against the as-is value with an eye toward the as-stabilized scenario. The borrower's business plan — renovation scope, lease-up timeline, rent growth assumptions — is analyzed but the asset exists as tangible collateral from day one.
Bridge loans in 2026 are priced at SOFR + spread, with all-in rates of 8–14% depending on asset type, LTV, and sponsor strength. Terms run 12–36 months, with extension options common in institutional products. Recourse varies: construction-to-bridge (where a bridge loan takes out a construction loan at completion) may retain full recourse during lease-up; acquisition bridge loans on stabilized assets may be limited recourse or non-recourse with carve-outs. For a complete bridge loan product overview, see institutional bridge loans.
Construction Loan vs. Bridge Loan: Side-by-Side Comparison
| Factor | Construction Loan | Bridge Loan |
|---|---|---|
| Primary Purpose | Fund ground-up construction or major rehab | Carry transitional / existing asset to stabilization or sale |
| Typical Term | 18–30 months | 12–36 months |
| Rate Structure | Floating (SOFR + spread) | Floating (SOFR + spread) |
| Rate Range (2026) | 8.5–11% all-in | 8–14% all-in |
| Recourse | Almost always full recourse + completion guaranty | Varies: full to non-recourse with carve-outs |
| LTC / LTV | 65–75% of total project cost | 70–80% of as-is value (higher on stabilized) |
| Underwriting Basis | Plans, budgets, sponsor track record, market analysis | As-is value, as-stabilized value, business plan |
| Draw Schedule | Yes — milestone-based draws with inspector sign-off | Typically no — fully funded at close (or revolving) |
| Exit | Bridge loan takeout or permanent refi at completion | Permanent refi or sale at stabilization |
| JV Equity Interaction | Equity in first; draws fund pro-rata or after equity | Equity contributes to acquisition; bridge funds acquisition + capex |
Data Visualization
Typical Financing Instrument by Project Phase (North Fulton, 2026)
* Illustrative project phase timeline. Actual timelines vary by asset type and market conditions.
Sequencing: How Construction and Bridge Financing Interact
On a ground-up development project, construction and bridge financing are sequential instruments — not competing alternatives. The construction loan funds the build; a bridge loan (or mini-perm) takes out the construction loan at project completion and carries the asset through lease-up to the point where it qualifies for permanent financing.
This sequencing creates a multi-phase financing timeline. Consider a 200-unit multifamily development in North Fulton County: the construction loan closes at project launch, funding a 24-month build period. At construction completion, the asset is delivered but only 30% occupied — well short of the 90%+ stabilized occupancy required for agency permanent debt. The operator takes out the construction loan with a 24-month bridge loan (at SOFR + 450, or approximately 9.8%), using the bridge period to lease up the property. At 92% occupancy, the operator refinances into a Fannie Mae or Freddie Mac permanent loan at a fixed rate.
The alternative — a mini-perm — is a hybrid product that some construction lenders offer as an extension of the construction loan, converting to a short-term permanent loan (typically 3–5 years, fixed or floating) at completion. Mini-perms avoid the refinancing friction of a separate bridge loan closing but are often less flexible than standalone bridge products and may carry conversion fees or spread adjustments.
Rate exposure during the transition from construction to bridge is a material risk. If SOFR moves significantly between construction loan closing and bridge loan closing, the effective cost of the bridge may be higher or lower than projected at deal underwriting. Operators should stress-test financing assumptions at both floors and ceilings of realistic rate scenarios across the full project timeline.
How JV Equity Layers Into Both Structures
In a JV construction deal, equity is contributed first — lenders require proof that equity is fully committed and available before the first construction draw. The LP and GP contribute their respective equity shares at or before closing; the construction lender then advances draws in sequence as milestones are hit. Most institutional construction lenders require an equity-in-first funding order for the first portion of draws, ensuring the operator's skin-in-the-game is real before lender exposure begins.
LP investors in construction JVs bear all construction-phase risks: completion risk (will the building get built?), cost overrun risk (will budget hold?), floating rate risk (will construction loan costs escalate?), and market risk (will the market absorb the product at projected rents?). This risk profile is why institutional LPs require higher preferred return hurdles on construction deals (often 8–10%) versus stabilized acquisitions (6–8%).
In a bridge loan deal, equity is contributed at acquisition — the bridge lender advances the balance of the acquisition price plus any reserved renovation capex. The LP contributes equity at close; the bridge loan funds the rest. LP risk on a bridge deal is lower than on construction (the asset exists) but higher than on a stabilized permanent loan deal (the business plan must execute).
For a comprehensive view of capital stack construction across construction and bridge phases, see real estate capital stack explained and our high-leverage debt ratios guide.
Quick Check
See what capital you qualify for in under 3 minutes.
No origination fees for initial capital review. Institutional structures available.
Check Capital Eligibility →Frequently Asked Questions
What is a construction loan in real estate?
What is a bridge loan used for in real estate?
Can I use bridge financing during construction?
What is a mini-perm loan?
How does JV equity work alongside a construction loan?
Ready to access institutional JV capital for your next deal?
Pillar Partners connects qualified operators with institutional capital for joint ventures, mezzanine financing, and bridge loans across North Fulton County, GA. No origination fees for initial submissions.
Affiliate disclosure: Pillar Partners may earn a referral fee when you access capital through our partners. See our full disclosure policy.
Begin Capital Review →